Showing posts with label scam. Show all posts

Tuesday, March 18, 2014

Eleven Bankers + BitCoin's Radtke makes TWELVE D.O.A just call it FOURTEEN Now!! Top JPMorgan L:awyer DEAD

28-Year Old Former JPMorgan Banker Jumps To His Death, Latest In Series Of Recent Suicides

Tyler Durden's picture


Not a week seems to pass without some banker or trader committing suicide. Today we get news of the latest such tragic event with news that 28-year old Kenneth Bellando, a former JPMorgan banker, current employee of Levy Capital, and brother of a top chief investment officer of JPM, jumped to his death from his 6th floor East Side apartment on March 12.

From the NY Post:
Bellando, a former investment bank analyst at JPMorgan, is the son of John Bellando, chief operating officer and chief financial officer at Condé Nast. His brother, John, a top chief investment officer with JPMorgan, works on risk exposure valuations.

Several John Bellando emails were cited during testimony at the Senate Finance Committee’s inquiry into the bank’s losses during the infamous London Whale trade fiasco.

Kenneth Bellando — who grew up in Rockville Center, LI, and was a Georgetown graduate — worked as a summer analyst at JPMorgan while in school. Upon graduation in 2007, he was hired as an investment bank analyst and worked there for one year before moving on, according to his LinkedIn page.

The investment banker then went to Paragon Capital Partners, according to his LinkedIn page, until leaving at the end of 2013.
And so another young life is tragically taken before his time, the 11th financial professional to commit suicide in 2014, and the third in as many weeks. How many more to come?
In summary, here are all the recent untimely financial professional deaths we have witnessed in recent months:
1 - William Broeksmit, 58-year-old former senior executive at Deutsche Bank AG, was found dead in his home after an apparent suicide in South Kensington in central London, on January 26th.
2 - Karl Slym, 51 year old Tata Motors managing director Karl Slym, was found dead on the fourth floor of the Shangri-La hotel in Bangkok on January 27th.
3 - Gabriel Magee, a 39-year-old JP Morgan employee, died after falling from the roof of the JP Morgan European headquarters in London on January 27th.
4 - Mike Dueker, 50-year-old chief economist of a US investment bank was found dead close to the Tacoma Narrows Bridge in Washington State.
5 - Richard Talley, the 57 year old founder of American Title Services in Centennial, Colorado, was found dead earlier this month after apparently shooting himself with a nail gun.
6 - Tim Dickenson, a U.K.-based communications director at Swiss Re AG, also died last month, however the circumstances surrounding his death are still unknown.
7 - Ryan Henry Crane, a 37 year old executive at JP Morgan died in an alleged suicide just a few weeks ago.  No details have been released about his death aside from this small obituary announcement at the Stamford Daily Voice.
8 - Li Junjie, 33-year-old banker in Hong Kong jumped from the JP Morgan HQ in Hong Kong this week.
9 - James Stuart Jr, Former National Bank of Commerce CEO, found dead in Scottsdale, Ariz., the morning of Feb. 19. A family spokesman did not say whatcaused the death
10 - Edmund (Eddie) Reilly, 47, a trader at Midtown’s Vertical Group, commited suicide by jumping in front of LIRR train
11 - Kenneth Bellando, 28, a trader at Levy Capital, formerly investment banking analyst at JPMorgan, jumped to his death from his 6th floor East Side apartment.


Bitcoin CEO found dead in Singapore, suicide suspected
Published time: March 06, 2014 09:53
Edited time: March 07, 2014 10:36

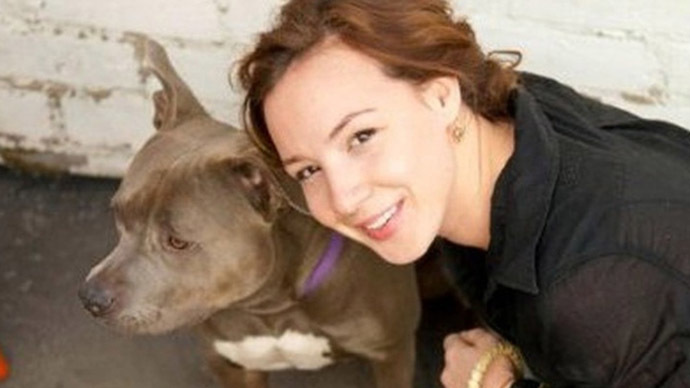
Autumn Radtke (Photo from linkedin.com)
A young American woman who ran the First Meta bitcoin exchange was found dead in her Singapore apartment last week. Police are investigating the “unnatural death”.
Autumn Radtke was found on the morning of February 26 after Police received an emergency call from an apartment building. She was pronounced dead at the scene. A preliminary police investigation has ruled out foul play, but neighbors told police they suspected Radtke jumped from an apartment.
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~


JP Morgan’s Top Commercial Bankruptcy Lawyer Dead In Minivan Hit & Run

By
Updated: March 28, 2014
bicycle accident

JP Morgan’s Top Commercial Bankruptcy Lawyer Dead In Minivan Hit & Run via TruNews

The banker suicide saga has just reached a new level as a top level JPMorgan attorney has been exterminated in a hit & run incident involving a minivan.
JPM attorney Joseph Giampapa was killed over the weekend when he was struck by a minivan in a hit and run incident.  Giampapa was reportedly hit and thrown 150 ft and was pronounced dead at the scene.  No charges have been filed.
It gets better:  Giampapa was JPMorgan’s top commercial bankruptcy lawyer (SVP).
Somehow we suspect the incident was not inflicted by a soccer mom.
Read Full Article

Dublin Cyclist Killed During Biking Trip In Miami County

Joseph Giampapa was riding alone on Troy-Sidney Road when he was struck by a car at about 11:08 a.m. Saturday morning.
The driver of the car called 911 and Miami County Sheriff deputies responded to the scene. Giampapa was found lying in the driveway of a home located in the 6500 block of Troy-Sidney Road in Springcreek Township.
He was pronounced dead at the scene by medic personnel.
Deputies say Giampapa was taking part in a 200 mile bike ride with a bicycle club named Ohio Randonneurs.
Their route started in Springfield and went through Troy, then reversed course.  Deputies believe Giampapa was on his return trip when the crash occurred.
“Joe was an extremely accomplished cyclist a responsible cyclist and that’s what makes this tragedy so mind numbing,” said Jeff Stephens, a friend of Giampapa. “That road that Joe was on was flat. No trees. It was just wide open visibility.”


Sunday, March 2, 2014

the S&L scandal was the largest theft in the history of the world

In the early 1980s, under Reagan, regulatory changes took place that gave the S&L industry new powers and for the first time in history measures were taken to increase the profitability of S&Ls at the expense of promoting home ownership.
A history of the S&L situation can be found here:
http://www.fdic.gov/bank/historical/s&l/

 Following the deregulation of savings and loan associations (S&Ls) in the early 1980's, several of these banks began taking greater liberties with depositors' money, sinking it into risky real estate ventures and junk bonds in an effort to reap maximum profits. Fearful about the future of the vast amounts of federally-insured money being invested, the Federal Home Loan Bank Board (FHLBB) instituted a cap on the amount of money S&L's were allowed to place in such volatile instruments. An investigation into Lincoln Savings and Loan uncovered flagrant violations of these regulations, exceeding the limit by over $615 million.
But before any measures could be taken against the company, five Senators came calling at the FHLBB, requesting that the charges against Lincoln not be pursued, on the basis that the S&L was a major employer in their states. These Senators — McCain , John Glenn (D-OH), Alan Cranston (D-CA), Donald Riegle (D-MI) and Dennis DeConcini (D-AZ) — had little in common. Most of them came from different states and different parts of the political spectrum. One of the only elements that linked the men together was Charles Keating. The banker had been a major contributor to each of their campaigns, donating close to $1.4 million dollars total. Keating also considered John McCain to be a close personal friend, with whom he'd shared vacations and business ventures.
Their pleas bought Lincoln more time, but the company was ultimately seized by the FHLBB two years later. Its bailout cost taxpayers over $3 billion; thousands of Lincoln investors lost their life savings.
The magnitude of Lincoln's collapse and the fraud charges later brought against Keating led the Senate Ethics Committee to launch an investigation into the conduct of the five Senators — now known as the Keating Five —

Read more: The Keating Five - TIME http://content.time.com/time/business/article/0,8599,1848150,00.html#ixzz2usVZsCu3


What is important to note about the S&L scandal is that it was the largest theft in the history of the world and US tax payers are who was robbed.
The problems occurred in the Savings and Loan industry as they relate to theft because the industry was deregulated under the Reagan/Bush administration and restrictions were eased on the industry so much that abuse and misuse of funds became easy, rampant, and went unchecked.
Additional facts on the Savings and Loan Scandal can be found here:
http://www.inthe80s.com/sandl.shtml
There are several ways in which the Bush family plays into the Savings and Loan scandal, which involves not only many members of the Bush family but also many other politicians that are still in office and still part of the Bush Jr. administration today.  Jeb Bush, George Bush Sr., and his son Neil Bush have all been implicated in the Savings and Loan Scandal, which cost American tax payers over $1.4 TRILLION dollars (note that this is about one quarter of our national debt).

 http://rationalrevolution.net/war/bush_family_and_the_s.htm

“This bill is the most important legislation for financial institutions in the last 50 years. It provides a long-term solution for troubled thrift institutions. ... All in all, I think we hit the jackpot.” So declared Ronald Reagan in 1982, as he signed the Garn-St. Germain Depository Institutions Act.

Reagan-era legislative changes essentially ended New Deal restrictions on mortgage lending — restrictions that, in particular, limited the ability of families to buy homes without putting a significant amount of money down. 
Paul Krugman

Government, declared Reagan, is the problem, not the solution; the magic of the marketplace must be set free. And so the precautionary rules were scrapped.
Together with looser lending standards for other kinds of consumer credit, this led to a radical change in American behavior.
We weren’t always a nation of big debts and low savings: in the 1970s Americans saved almost 10 percent of their income, slightly more than in the 1960s. It was only after the Reagan deregulation that thrift gradually disappeared from the American way of life, culminating in the near-zero savings rate that prevailed on the eve of the great crisis. Household debt was only 60 percent of income when Reagan took office, about the same as it was during the Kennedy administration. By 2007 it was up to 119 percent.
 Savings and Loans Crisis


Disaster struck after Paul Volcker, then chairman of the Federal Reserve Board, decided in October 1979 to restrict the growth of the money supply, which in turn caused interest rates to skyrocket. Between June 1979 and March 1980 short-term interest rates rose by more than six percentage points, from 9.06 percent to 15.2 percent. In 1981 and 1982 combined, the S&L industry collectively reported almost $9 billion in losses. Worse, in mid-1982 all S&Ls combined had a negative net worth, valuing their mortgages on a market-value basis, of $100 billion, an amount equal to 15 percent of the industry’s liabilities. Specific policy failures during the 1980s are examined below.
An incomplete and bungled deregulation of S&Ls in 1980 and 1982 lifted restrictions on the kinds of investments S&Ls could make. In 1980 and again in 1982, Congress and the regulators granted S&Ls the power to invest directly in service corporations, permitted them to make real estate loans without regard to the geographical location of the loan, and authorized them to hold up to 40 percent of their assets as commercial real estate loans. Congress and the Reagan administration naïvely hoped that if S&Ls made higher-yielding, but riskier, investments, they would make more money to offset the long-term damage caused by fixed-rate mortgages. However, the 1980 and 1982 legislation did not change how premiums were set for federal deposit insurance. Riskier S&Ls still were not charged higher rates for deposit insurance than their prudent siblings. As a result, deregulation encouraged increased risk taking by S&Ls.

 December, 1982--Garn - St Germain Depository Institutions Act of 1982 enacted. This Reagan Administration initiative is designed to complete the process of giving expanded powers to federally chartered S&Ls and enables them to diversify their activities with the view of increasing profits. Major provisions include: elimination of deposit interest rate ceilings; elimination of the previous statutory limit on loan to value ratio; and expansion of the asset powers of federal S&Ls by permitting up to 40% of assets in commercial mortgages, up to 30% of assets in consumer loans, up to 10% of assets in commercial loans, and up to 10% of assets in commercial leases.
 www.fdic.gov/bank/historical/s&l/‎

Inflation was high when Volcker took over-13% or so. To get it under control, he tightened the money supply. This brought on a monster recession, the biggest since World War II. Within a year, the prime rate shot up to the unheard-of level of 21.5% (compared to an average of 7.6% for the fourteen previous years). Unemployment peaked at just under 11%.

According to author Robert Sherrill, Volcker stated, upon taking office, that "the standard of living for the average American has to decline." Sherrill says Volcker was recommended by David Rockefeller because "Wall Street and the international banking fraternity loved [Volcker]. They hated inflation-bankers don't like to be repaid in money that is softer than the money they lend, even if the softer money makes the economy hum-and they knew that Volcker was mean enough to destroy the economy to save the hardness of their dollars."

Volcker's policies caused a combination of inflation and recession called "stagflation." This put the squeeze on S&Ls. Most S&L mortgages were fixed-rate, so the S&Ls couldn't raise the interest they charged on those.

But because their depositors were withdrawing money by the billions and placing it in higher-yielding money market funds or government bonds, the S&Ls did have to raise the rates they paid on savings accounts and CDs. Finally, because of the recession, homeowners started defaulting on their mortgages in droves, and S&L bankruptcies skyrocketed.

 Around the same time, the Reagan administration ended the requirement that S&Ls lend money only in their own communities, allowed them to offer 100% financing (i.e. no down payments), let real estate developers own their own S&Ls, and permitted S&L owners to lend money to themselves.

 Scoundrel time

Whatever truth there is to that rumor the "defraud me" sign worked. J. William Oidenburg bought State Savings of Salt Lake City for $10.5 million, then had it pay him $55 million for a piece of land he'd bought for $874,000.

With the help of a shadowy figure named Herman K. Beebe, who served a year for bank fraud, Don Dixon bought Vernon Savings and Loan-one of the nation's healthiest-then set up a series of corporations for it to loan money to. Four years later, he left Vernon $1.3 billion in debt.

Beebe also had money in Silverado Savings, an S&L partly owned by President Bush's son Neil. Silverado told a prospective borrower he couldn't have $10 million; instead, he should borrow $15 million and buy $5 million in Silverado stock.

Although federal examiners knew Silverado was leaking cash as early as 1985, it wasn't closed down until December 1988, a month after Bush was elected president. Because Silverado kept leaking cash for those three years, it ended up costing taxpayers more than a billion dollars

 http://www.thirdworldtraveler.com/Corporate_Welfare/S%26L_Bailout.html

 In April 1987, as the world of savings and loan associations teetered under the weight of a boom in commercial real-estate lending, a group of senators met twice with federal banking regulators on behalf of Charles H. Keating, Jr., whose bank later collapsed at a cost to taxpayers of $3 billion. The senators -- Alan Cranston of California, John Glenn of Ohio, Dennis DeConcini and John McCain of Arizona, and Donald W. Riegle of Michigan (who attended only one of the meetings) -- had collectively received $1.3 million in campaign contributions from Mr. Keating, and their actions later became the subject of a lengthy ethics investigation into what became known as the case of the Keating Five. In 1991, the Senate censured Mr. Cranston and reprimanded the others for "poor judgment.''

 The Keating Five were five United States Senators accused of corruption in 1989, igniting a major political scandal as part of the larger Savings and Loan crisis of the late 1980s and early 1990s. The five senators – Alan Cranston (Democrat of California), Dennis DeConcini (Democrat of Arizona), John Glenn (Democrat of Ohio), John McCain (Republican of Arizona), and Donald W. Riegle, Jr. (Democrat of Michigan) – were accused of improperly intervening in 1987 on behalf of Charles H. Keating, Jr., Chairman of the Lincoln Savings and Loan Association, which was the target of a regulatory investigation by the Federal Home Loan Bank Board (FHLBB). The FHLBB subsequently backed off taking action against Lincoln.

Lincoln Savings and Loan collapsed in 1989, at a cost of over $3 billion to the federal government. Some 23,000 Lincoln bondholders were defrauded and many investors lost their life savings. The substantial political contributions Keating had made to each of the senators, totaling $1.3 million, attracted considerable public and media attention. After a lengthy investigation, the Senate Ethics Committee determined in 1991 that Cranston, DeConcini, and Riegle had substantially and improperly interfered with the FHLBB’s investigation of Lincoln Savings, with Cranston receiving a formal reprimand. Senators Glenn and McCain were cleared of having acted improperly but were criticized for having exercised “poor judgment”.


Thursday, February 6, 2014

Four International Bankers, Now another found dead as "Suicides".

  Four Prominent Bankers Found Dead Within Six Days, All Ruled ‘Suicides’


bankers-dead
What’s going on? Top officials from JPMorgan Chase, Deutsche Bank, and the Federal Reserve have all turned up dead over the course of six days.

Each was ruled by coroners to have taken their own lives.
Former Federal Reserve economist Mike Dueker has made the fourth in a growing and bizarre list of dead international bankers. Dueker was just found dead at his home near Tacoma, Washington.

 Dueker, 50, was a chief economist at Russell Investments. He had been missing since January 29th. Anonymous sources said that he had been having troubles at work, but no further details, nor sources were disclosed.
 
A week ago, on Sunday, William Broeksmit, 58, a former senior manager for Deutsche Bank, was found dead in his home as well. He was hanging from a rope, in what was ruled a suicide as well.
The very next day, on January 27th, Tata Motors managing director Karl Slym, 51, was also found dead on the fourth floor of the Shangri-La hotel in Bangkok, Thailand. Police there are ruling it a suicide, but have not explained why. Slym was staying on the 22nd floor with his wife, and had not shown any signs of being suicidal.
On Tuesday, Gabriel Magee, 39, the vice president at JPMorgan Chase & Co’s (JPM) London headquarters, was said to have killed himself as well, in the Canary Wharf area. He apparently jumped off a building, in what was also ruled a suicide.
What do you think? Is there something strange going on here, or are these deaths simply the result of the stresses of a struggling economy?
(By M.B. David; stock image via Getty)

 
The Ticker

JPMorgan global program trading exec, dead at 37

Held flawless trading record

Ryan Henry Crane, 37, executive director in JPMorgan Chase & Co.'s (JPM) global program trading, died Feb. 10.

Details of the Stamford, Conn., native’s death have not been disclosed. He is survived by his wife, son and parents.

Crane’s death comes after a rash of suicides among three prominent bankers over the course of a week at the end of January and start of February, as well as the questionable suicide of a real estate finance executive said to have killed himself by shooting himself with a nail gun “seven or eight times.”
HousingWire first reported Feb. 1 that three prominent bankers were found dead in apparent suicides spanning the course of just six days.

Since then, details emerged about the work of the three that suggests at least a passing commonality – that is, the institutions they worked for were all connected to investigations in the United States or the United Kingdom for various types of fraud or misconduct.

Former Federal Reserve economist Mike Dueker, 50, was found dead in an apparent suicide near Tacoma, Washington on Jan. 31. Dueker was chief economist at Russell Investments.
On Jan. 26, William Broeksmit, 58, a former senior manager for Deutsche Bank, was found hanging in his home, also an apparent suicide.

On Jan. 28, Gabriel Magee, 39, vice president at JPMorgan’s London headquarters, apparently jumped to his death from a building in the Canary Wharf area.

The Metropolitan Police in London have opened up an investogation into Magee's death, which is something they only do when they don't find enough evidence for a death to be ruled a suicide.
(Hat tip to Zero Hedge.)

  We are shattered beyond words': Parents of JP Morgan executive who fell 500ft from bank's HQ demand answers

Gabriel Magee's parents are now demanding answers to how he could have got up on to the roof of the building in Canary Wharf

The parents of a JP Morgan executive who plunged to his death from the top of the bank’s London headquarters have today told of their grief.
American Gabriel Magee, 39, who fell over 500ft had worked as Vice President in the technology department for six years.

He was said to be in a happy relationship with a long-term girlfriend.
His parents, Bill, 64, and Nell, 74, Magee are now demanding answers to how he could have got up on to the roof of the building in Canary Wharf before he fell 500ft on Tuesday morning.
“We are shattered beyond words. This was a young man, we cherished him,” said Mrs Magee, 74.
“He was named after the angel Gabriel, the messenger who always had good news. He always brought us good news.”

Speaking to the Evening Standard from their home in Albuquerque, New Mexico yesterday (Wed), Mrs Magee said that the couple now plan to travel to London in search of answers.
She said: “I’ve spoken to the embassy, the police. I want to know the truth. I want to know what happened.
“How was he able to get up there. There was no reason for him to be up on that roof.”
The executive had recently agreed with his bosses that he could work four days a week instead of five and was thought to be planning a family with his partner.

His father, a former US military pilot, last spoke to his son a fortnight ago and said that he seemed content.
“It was very comforting to see him in a relationship that he thought had longevity,” he said.
IT expert Mr Magee was described as popular by colleagues with co-worker Joshua Konstadt calling the incident a terrible and tragic loss.
The Metropolitan police have also appealed for witnesses who may have seen him on the roof before the fall to contact them.

comment:
On Tuesday, Gabriel Magee, 39, the vice president at JPMorgan Chase & Co’s (JPM) London headquarters, was said to have killed himself as well, in the Canary Wharf area. He apparently jumped off a building, in what was also ruled a suicide.
 
"That's weird, my firm is located in Canary Wharf and I haven't heard a thing about it. It was not broadcasting either" 


http://www.mirror.co.uk/news/uk-news/gabriel-magee-death-jp-morgan-3091261#ixzz2sYtmqRq7
Follow us: @DailyMirror on Twitter | DailyMirror on Facebook


Thursday, April 21, 2011

IRS Funding Cut : $330 Billion Uncollected from Passport Holders


IRS Funding Cut Days Before Report Shows $330 Billion In Uncollected Taxes


First Posted: 04/11/11 06:03 PM ET Updated: 04/11/11 06:05 PM ET
WASHINGTON -- As part of the budget deal hashed out on Friday evening, lawmakers agreed that no additional federal funds would be used to hire new IRS agents.
Then on Monday, the Government Accountability Office publicly released a study showing that, as of the end of fiscal year 2010, roughly $330 billion in federal taxes had never been paid -- an amount that, if collected, would represent nearly nine times the amount of savings as the budget itself.
The dual developments aren’t shocking. Despite evidence that a single dollar spent on enforcing the tax code could result in up to ten dollars in revenue, politicians, naturally, are reluctant to align themselves with tax collectors. And yet, the sacrificing of funds for IRS agents in the continuing resolution deal underscores a particular problem that seems bound to confront fiscally conscious lawmakers.
“Cutting back on IRS enforcement could easily cost the treasury much more in revenue than it saves,” said Chuck Marr, Director of Federal Tax Policy at the Center on Budget and Policy Priorities.
The GAO report, which looks specifically at the issue of passport holders who have failed to pay their full share of taxes, underscores Marr’s point. Titled “Federal Tax Collection: Potential for Using Passport Issuance to Increase Collection of Unpaid Taxes,” the study labels poor enforcement of tax laws and the tax code as a “high-risk” hole in government policy. In fiscal year 2008, passports were issued to about 16 million individuals. Of those, more than 224,000 owed more than $5.8 billion in unpaid federal taxes.
A good chunk of the evasion, the GAO concluded, was committed by individuals with “substantial personal assets” including multi-million-dollar homes and “luxury cars.” One passport recipient bought a house for $2 million and another property for $1.5 million despite owing $1 million in federal taxes.
“If you look, you can find records of most capital gains income,” said Rob Shapiro, former U.S. Undersecretary of Commerce. “People deposit it in their bank accounts or the institutions may issue reports if it is capital gains on stock transactions. So it is not hard to pick it up if you have the manpower to look for it. And again, given that the salary of an IRS agent is at least as high as the average salary in America, the fact that there is a ten-to-one ratio for the returns on auditing tells you that [tax evasion] is coming from the high-income brackets.”
ADVERTISEMENT
Regardless of who the worst evaders are, the GAO concludes that “IRS enforcement of federal tax laws is vital,” not just to pinpoint the offenders but to promote “broader compliance.” And what do the study’s authors cite as a compelling reason to beef up IRS functions? A “federal deficit” that “continue[s] to mount.”
Indeed, several close observers of the budget debate have wondered exactly how lawmakers can shudder at going after tax evasion while simultaneously preaching fiscal responsibility on the stump. Marr, for one, noted that Congress has already disbanded a tax reporting provision in the president’s health care reform law that would have resulted in stronger compliance. That was scuttled for politically obvious reasons: the paperwork it placed on small businesses was deemed well beyond burdensome. But the decision to deny funding for more IRS agents doesn’t have such an easy-to-distill an explanation.
“Hiring more IRS agents would have allowed the Obama administration to enforce its agenda, insofar as its agenda is to make sure that people don't cheat on their taxes,” wrote Jonathan Cohn in The New Republic.
Obama has made buffing up the IRS a relative hush-hush plank of his tax reform agenda. Upon entering office he advocated for more funds for the agency, and as part of his 2012 budget, he proposed a 9.4 percent increase so that it could hire roughly 5100 new employees. The proposal, which pivoted off of previous studies that reached similar conclusions as the GAO's, was met with somewhat frenzied pushback from conservative circles -- the specter of black-suited tax collectors roaming the streets undoubtedly on the mind. And almost immediately, the suggested increase in IRS funds became a target of cut-happy legislators